Checking Accounts for Seniors: Fees, Safety, and Features
Everyday banking guide
How to choose a checking account that supports everyday needs
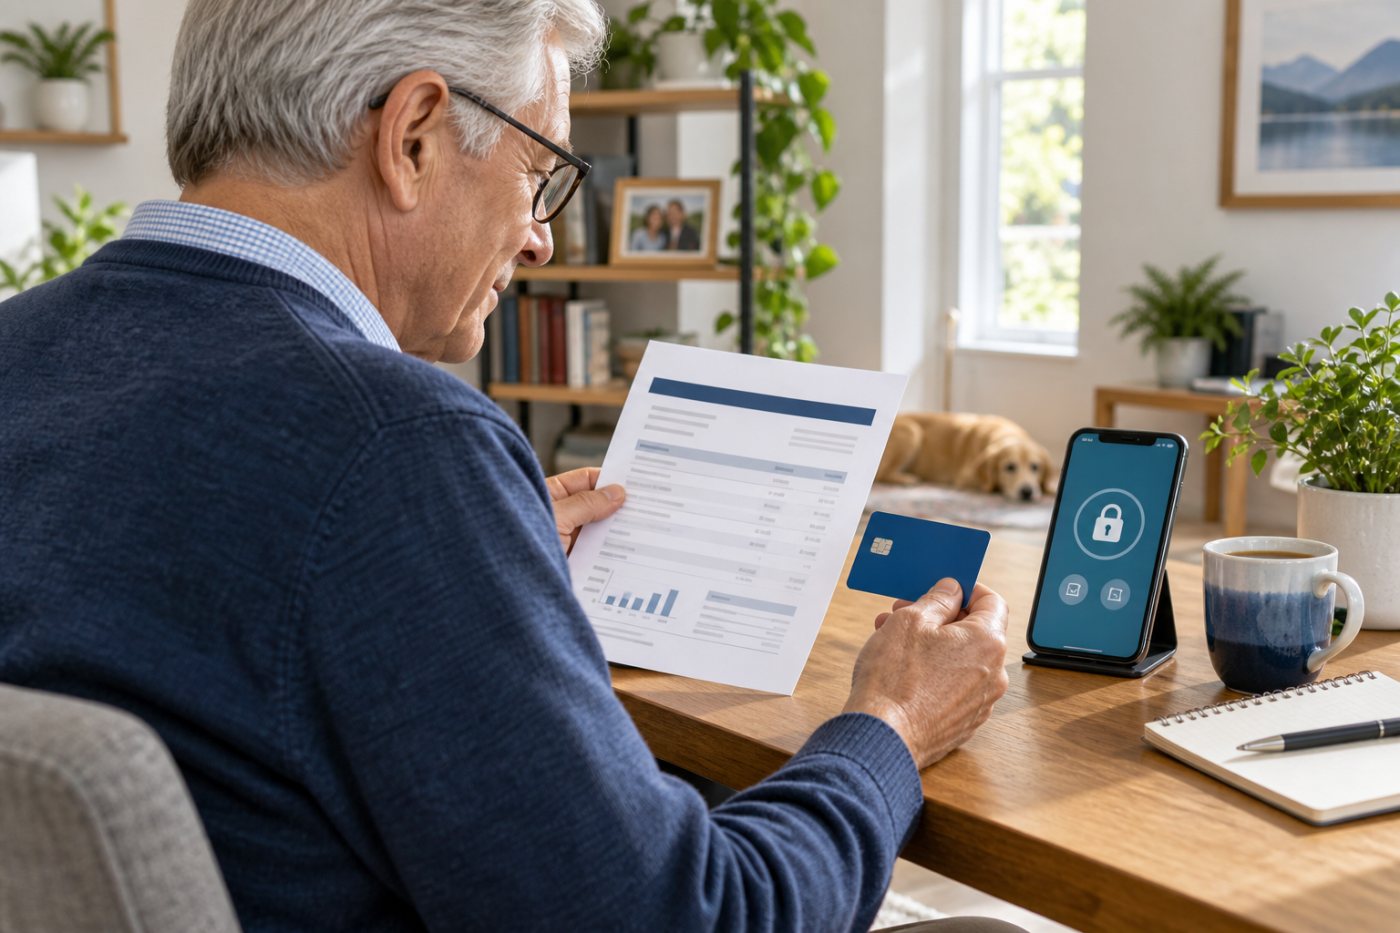
A checking account for seniors should make routine money management simple, affordable, and secure. The right choice depends on fees, access, account tools, and the support you prefer.
Key takeaways
- Compare monthly fees, overdraft practices, ATM access, and minimum-balance rules.
- Choose a bank or credit union whose service channels fit your routine.
- Use account alerts and strong login protection to reduce fraud risk.
- FDIC or NCUA deposit insurance protects eligible deposits up to applicable limits.
Checking accounts for seniors are often marketed with fee waivers or extra services, but the name alone does not make an account the best fit. Read the account disclosure and compare the features you will actually use.
Start with the costs
Look beyond the monthly service fee. Ask whether a fee can be waived, what balance is required, how out-of-network ATM fees work, and whether the account charges for paper checks, statements, or overdrafts. A no-fee account can still become expensive if its rules do not match how you bank.
| Feature | Why it matters | What to ask |
|---|---|---|
| Monthly fee | Can reduce funds available for everyday spending. | Can it be waived, and under what conditions? |
| ATM network | Convenient cash access may prevent extra charges. | Which ATMs are free, and are out-of-network fees reimbursed? |
| Overdraft policy | Unexpected transactions can trigger fees or declined payments. | What options, alerts, and fees apply? |
| Service access | Help should fit your preferences and mobility needs. | Are branches, phone support, and online tools available? |
Match access to your routine
Some people value a nearby branch and face-to-face service. Others prefer a credit union, online banking, mobile check deposit, or telephone support. Think about cash withdrawals, deposits, bill pay, caregiver coordination, and how easily you can reach help if a transaction looks unfamiliar.
Before opening an account, test the bank’s locator, support hours, and accessibility options. Ask how to obtain paper statements if you want them and whether they carry a fee. An account that is convenient on a normal day is usually easier to manage during a stressful one.
Use security tools that make sense
Turn on transaction and balance alerts, use a unique password, and enable multi-factor authentication when offered. Never share a one-time code with a caller or message sender. Your bank may contact you about suspicious activity, but you can independently call the number on the back of your debit card or use the bank’s official website to verify a request.
Understand deposit insurance
At an FDIC-insured bank, eligible deposits are insured up to the applicable limit. Federally insured credit unions have comparable coverage through the NCUA. Insurance coverage depends on ownership categories and other details, so use the official FDIC or NCUA tools for your specific situation rather than assuming every product is covered.
A practical account-opening checklist
- Review the fee schedule and account agreement.
- Confirm how you will access cash, statements, and support.
- Ask about overdraft choices before a problem occurs.
- Set up alerts and secure login protection.
- Keep your contact details current and review transactions regularly.
For a broader overview, visit our Banking guides.
Frequently asked questions
Are senior checking accounts always free?
No. Some accounts offer fee waivers, but conditions and other charges can still apply. Review the disclosure before opening an account.
Should I choose a bank or credit union?
Either can work. Compare insurance coverage, fees, convenience, branch access, and the services you prefer.
What is the safest way to use online banking?
Use the institution’s official website or app, unique passwords, multi-factor authentication, and account alerts.
Can I avoid overdraft fees?
Many institutions offer settings and alerts that can help. Ask about overdraft options and their costs when opening the account.
Is my money insured in a checking account?
Eligible deposits at FDIC-insured banks or federally insured credit unions generally have coverage up to applicable limits. Check official sources for your situation.