How to Dispute a ChexSystems Record After a Denial
If a bank denied your checking-account application because of ChexSystems, start by getting the report the bank used, identifying the exact error, and disputing it with both ChexSystems and the bank or credit union that supplied the information. A clear paper trail matters more than a long explanation.
A denial is a signal to review the underlying report—not proof that every item in it is correct.
- Keep the adverse-action notice; it identifies the consumer reporting company the bank used.
- Request your ChexSystems consumer disclosure and compare every entry with your records.
- Dispute inaccurate information with both ChexSystems and the financial institution that furnished it.
- State exactly what is wrong, attach copies of evidence, and ask for a specific correction or deletion.
- Most reinvestigations are normally completed within 30 days; preserve submission and delivery records.
- A successful correction does not guarantee that a bank will approve a new account.
What a ChexSystems denial means
ChexSystems is a specialty consumer reporting company focused on checking and savings account history. Its files may include account applications, openings and closures, unpaid negative balances, suspected fraud indicators, and the reason a financial institution reported an account closure. ChexSystems supplies information; the bank or credit union makes the account-opening decision.
When a bank denies an account based on a consumer report, the adverse-action notice should identify the reporting company and explain how to obtain a copy. The notice does not necessarily mean you did something wrong. A mixed file, an account created through identity theft, a duplicate entry, an incorrect balance, or an outdated status can all cause problems.
How to dispute a ChexSystems record in 7 steps
- Save the denial notice. Note the bank, application date, reporting company, and any reference number. Do not rely on memory or a phone conversation alone.
- Get your consumer disclosure. Request it through the official ChexSystems request page. The CFPB says nationwide checking-account reporting companies must provide a free report every 12 months, and a denial based on a report can also create a right to a free copy.
- Mark each disputed field. Compare the institution name, account number fragment, balance, dates, status, and reason for closure with your own records. Separate provably inaccurate information from accurate information you simply dislike.
- Collect supporting documents. Use copies—not originals—of statements, payment confirmations, closure letters, correspondence, police reports, or an FTC IdentityTheft.gov report. Redact information that is not needed for the dispute.
- Dispute with both parties. Submit a dispute to ChexSystems and a separate direct dispute to the bank or credit union that furnished the item. Explain the same facts consistently in both submissions.
- Track the investigation. Save screenshots, confirmation numbers, copies of letters, and delivery proof. Create a calendar reminder for the expected response window.
- Review the result before reapplying. Confirm that the corrected status appears in a fresh disclosure. If the investigation does not resolve a documented error, add a consumer statement and consider a CFPB complaint.

Build a small evidence packet that links every disputed field to a supporting document.
What errors should you look for?
A useful dispute identifies a factual problem. Common examples include an account that is not yours, an incorrect balance, a payment that was never reflected, a duplicate entry, the wrong closure date, an account marked unpaid after it was settled, or information caused by identity theft. Also check whether another consumer’s information appears in your file.
The CFPB notes that most negative information older than seven years generally cannot be included in a consumer report. ChexSystems says its current practice is generally to retain reported information for five years unless the source asks for removal or removal is required by law or policy. These are different concepts: a company’s ordinary retention practice does not replace your rights under federal or state law.
Build a precise dispute packet
| Include | Why it helps | Example |
|---|---|---|
| Item identification | Shows exactly what to investigate | Institution, partial account number, report date |
| Specific error | Avoids a vague or frivolous dispute | “Balance should be $0, not $240” |
| Supporting copy | Connects your claim to evidence | Paid-in-full letter or bank statement |
| Requested outcome | Makes the correction clear | Update balance, correct date, or delete an account that is not yours |
| Contact details | Allows authentication and response | Current name, address, and required identification |
ChexSystems’ official dispute page provides online and mail options. For mail, the current address listed by both ChexSystems and the CFPB is: Chex Systems, Inc., Attn: Consumer Relations, P.O. Box 583399, Minneapolis, MN 55458. Follow the current authentication instructions on the official page rather than copying an address from an old form.
How long does a ChexSystems dispute take?
ChexSystems says reinvestigations are usually completed within 30 days (21 days for Maine residents). Under the Fair Credit Reporting Act process described by the FTC, the standard window is generally 30 days, and a consumer reporting company may receive up to 15 additional days if you provide relevant new information during that period. A direct dispute to the furnisher is also generally investigated within 30 days.
Do not repeatedly send scattered documents without context. If new evidence is important, label it clearly and keep a dated copy. When the result arrives, compare it with the original report line by line.
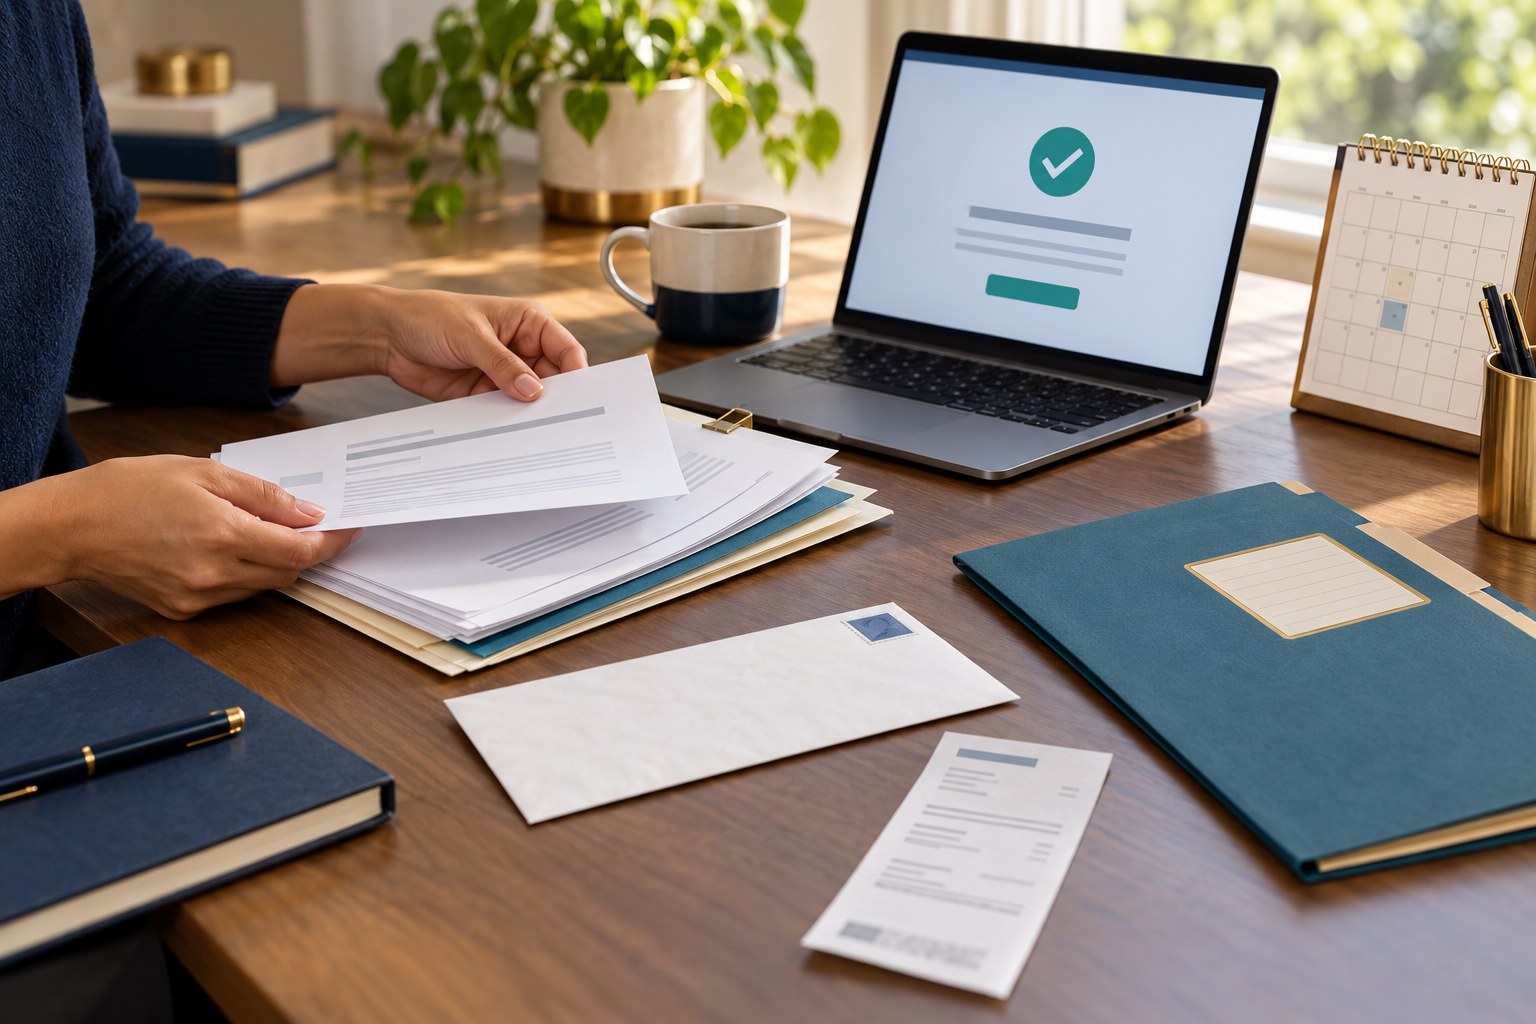
Keep confirmation numbers and delivery records until the disputed entry is corrected and verified.
If identity theft caused the record
Use the identity-theft process rather than treating the problem as a routine balance disagreement. Report the theft at IdentityTheft.gov, follow the recovery plan, and include the appropriate identity-theft documentation with your disputes. Consider a ChexSystems security freeze or alert if someone may still be trying to open deposit accounts in your name. A freeze limits release of the ChexSystems file without your authorization, but it applies only to that report.
What to do if the error remains
First, read the investigation result carefully: it may explain what was verified and by whom. Send any missing evidence to both ChexSystems and the furnisher, using the same precise description of the error. If you still disagree, you may be able to add a brief consumer statement to your file. You can also submit a complaint through the Consumer Financial Protection Bureau.
If the disputed information is accurate, paying an old balance may improve how the situation is viewed, but it does not automatically require deletion. Ask the reporting bank to update the status accurately. While the issue is pending, a local bank, credit union, or “second-chance” account may offer an alternative, but compare monthly fees, overdraft rules, and account restrictions before applying.
Frequently asked questions
How long does it take to dispute a ChexSystems record?
ChexSystems says reinvestigations are usually completed within 30 days, with a 21-day period for Maine residents. Relevant new information submitted during the process can affect the federal investigation window.
Does a corrected ChexSystems report guarantee a checking account?
No. A correction removes or updates inaccurate information, but each bank or credit union applies its own account-opening standards.
Can an accurate paid record be removed?
Payment does not automatically erase accurate history. Ask the furnishing institution to report the updated paid status accurately and confirm the change on a new disclosure.
Can I get my ChexSystems report for free?
Yes. ChexSystems provides consumer disclosure reports free of charge, and CFPB guidance explains additional free-report rights after an adverse action.
What if the ChexSystems entry came from identity theft?
Report the theft at IdentityTheft.gov, dispute the fraudulent item with ChexSystems and the furnishing institution, include the requested identity-theft documents, and consider a security freeze or alert.
Official sources
- CFPB: Disputing an error on a checking-account consumer report
- CFPB: ChexSystems company profile and consumer rights
- ChexSystems: Submit a dispute
- FTC: Consumer-report dispute duties and timelines
- FTC: What to know about identity theft
This article is general educational information for U.S. consumers, not legal or financial advice. Rights, deadlines, and procedures may vary by facts and state law. Use the current instructions on official agency and ChexSystems pages.